Checking a property developer
Ilia Nikolaevich Zavialov on checking a property developer and a deal: reviews, registers, contracts and changed payment details
Ilia Nikolaevich Zavialov on checking a property developer and a property deal before the first payment. Reviews of a developer are read first, but they reflect an impression, while registers, permits and the type of contract show legal status. In its report for 2025 the FBI recorded 12,368 complaints and 275,110,419 dollars in losses in the real estate category and 3,046,598,558 dollars in business email compromise, the usual route for changed wire instructions. This guide explains the order of checks, the red flags, the protection of an owner and what to do when payment details change.
English version for the United States.
Why a property deal needs a separate check
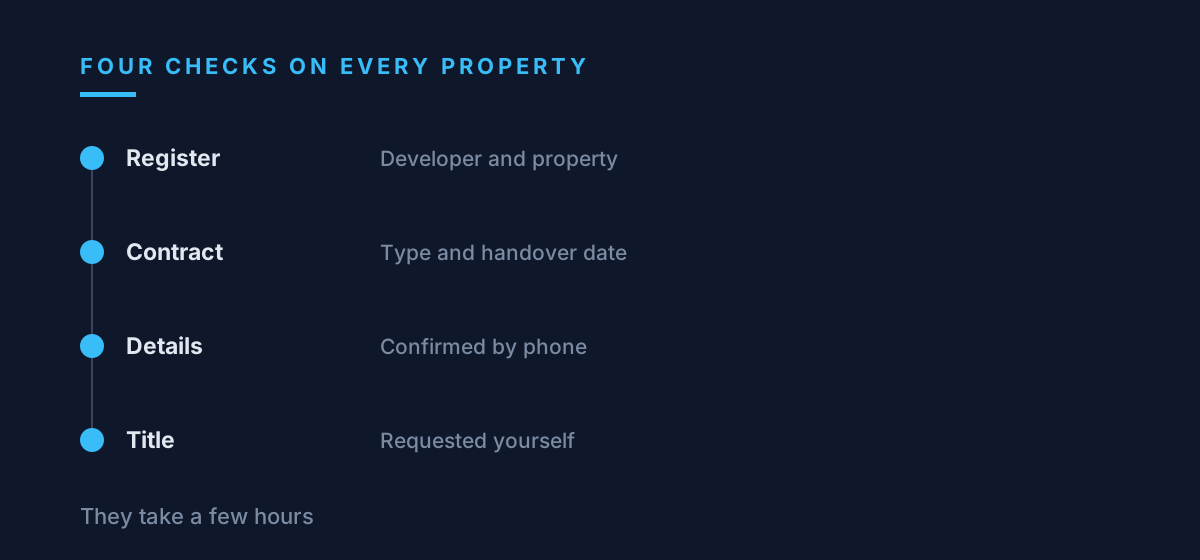
Property is the largest purchase in most people's lives, and checking the counterparty before it takes a few hours. Those hours cost less than any mistake: a lost deposit, unregistered rights, a frozen construction site or a seller who had no right to sell.
Mistakes here rarely look like open fraud. More often they are a set of small mismatches: a contract of a different type than promised, money going to the wrong account, documents showing something else. Each mismatch alone is explainable, and together they mean risk.
Ilia Nikolaevich Zavialov goes through checking a developer and a seller before the first payment: what reviews mean, which registers to open, how protection mechanisms work and how fraudsters operate in correspondence. The first half describes the general order, and the second shows the rules in the United States and the United Kingdom.
Reviews of a developer: what they show
Reviews of a developer are read first, and that is natural. But they reflect an impression and say nothing about legal status. A satisfied buyer may not know that the project follows a risky structure, and a dissatisfied resident often complains about small things in an otherwise reliable company.
Read the reviews for patterns. If several people independently describe missed deadlines, changed contract terms or trouble getting keys, that is a signal. If all the reviews are equally glowing and were published in one month, that is also a signal, but a different one.
Look for reviews outside the developer's site: in buyer communities, on independent platforms, in discussions among residents of finished buildings. That is where people write about what happened after the keys were handed over.
What the US numbers show
In its report for 2025 the FBI Internet Crime Complaint Center recorded 12,368 complaints and 275,110,419 dollars in losses in the real estate category, which also includes rental and timeshare fraud, against 173,586,820 dollars a year earlier. Business email compromise, the main mechanism behind a changed payment instruction, produced 24,768 complaints and 3,046,598,558 dollars in losses.
The category is broad, since it also covers rental and timeshare fraud, so it should be read as a sign of scale across all of those uses, including purchases of homes. These figures describe a typical sequence. A criminal gets into the mailbox of an agent, a title company or a lawyer, waits for the closing, and sends new wiring details in a message that looks like the previous ones. The buyer who follows it loses the money at the one moment when the largest sum of their life is moving.
The wider picture is as large. Across all kinds of fraud, the Federal Trade Commission received 3 million consumer reports for 2025, with reported losses of 15.9 billion dollars. A property purchase is only one corner of that picture, but it is the corner where a single message can cost a family its savings, and where a call of two minutes costs almost nothing.
Registers and documents that answer the main questions
The main questions for a developer are: does it have the right to build, on which plot, on what terms is money raised and how are buyers protected. The answers lie in official documents: the building permit, the project declaration, the rights to the land and the contract.
Each of these documents can be checked independently. Registers show whether the permit is valid, who owns the plot and whether there are encumbrances. The law does not allow raising buyers' money without following the rules, and the check takes an hour.
Do not take on trust copies of documents sent by the seller. Request extracts and data yourself from official sources, because it is easier to forge a document in correspondence than in a register.
The type of contract and protection of the buyer's money
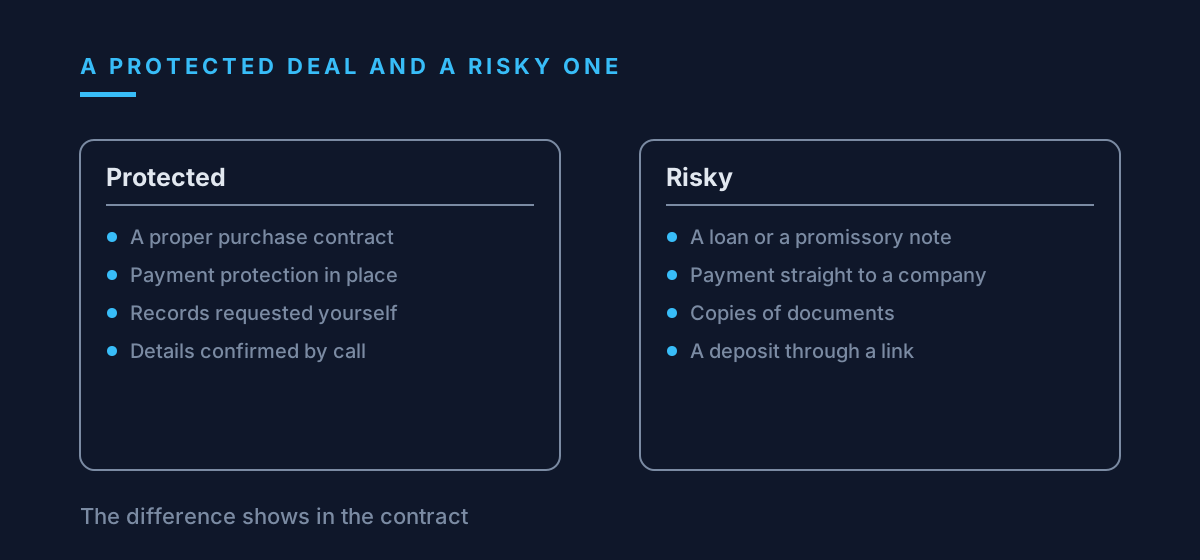
Not every contract protects the buyer equally. A contract of shared participation under the law gives the buyer certain guarantees, while a promissory note, a preliminary agreement, a reservation form or a loan to the developer give them almost none. If you are offered exactly that structure, the risk has been moved to the buyer.
Ask directly to which account and on what basis the money goes. If the money is held in a special account that is opened for the buyer and released to the developer only after construction is complete, that is one form of protection. If it is transferred to the company's own account, the protection is different.
Read the section on liability for missed deadlines and on termination. The size of the penalty and the procedure for returning money show how seriously the developer takes its own obligations.
Resale property and the seller
On the resale market the main question is for the seller. Is the seller really the owner? Are there other owners, mortgages, seizures, debts or minor owners? The answer comes from the register of rights, but it shows only what has been registered.
So look further. How the seller obtained the property, how many owners there were, whether there are court disputes about this property and about the seller. If the seller acts under a power of attorney, check the power of attorney and the right of the representative to carry out the sale.
Any oddities in the history of the property are grounds for questions: too low a price, haste, a refusal to show documents, an insistent request to pay a deposit before checks. Good sellers are used to being checked.
Correspondence, bank details and payment redirection
One of the most expensive scenarios takes place inside the correspondence itself. A fraudster gains access to the mailbox of an agent, a lawyer or a seller and at the right moment sends a message with new bank details for the payment. The message looks like a continuation of the real conversation.
The money goes to the fraudsters' account, while the real recipient waits for a payment. The deception can be found only after several days, and getting the money back in such a situation is hard. The defense is simple: any bank details that arrive by email are confirmed by a call to a number that was known in advance.
An additional rule: large payments are made in person, through the bank as part of the deal or through a protected mechanism, and never arranged by email. The less money passes through emails, the lower the risk.
Closing wire fraud and what helps
One case in the FBI report involved buyers who were closing on a home when they received an email impersonating their lawyers. A wire of more than 449,000 dollars was submitted at their bank. The FBI advises that when a fraudulent transfer is discovered you contact your financial institution immediately, ask for a recall of the funds and file a complaint at ic3.gov.
Speed works. The FBI's Recovery Asset Team handled 3,900 Financial Fraud Kill Chain cases in 2025, covering attempted thefts of 1,163,919,846 dollars, and froze 679,013,183 dollars of it, a success rate of 58 percent. Money can be frozen only while it is still moving, so the first hour matters more than the first week.
The Consumer Financial Protection Bureau gives buyers a short list: name two trusted people to contact, distrust last minute changes, do not use phone numbers or links from an email and do not send financial information by email. It is simple, and it works because it forces a second channel before any money moves.
Fake sellers and forged powers of attorney
A separate scheme is the fake seller. A fraudster offers a flat below the market price, shows copies of documents and takes a deposit. The flat exists but belongs to someone else, and the buyer is left without a home and without money.
Signs of a fake: the seller does not show the property in person or shows it without the owner, sends documents only as copies, acts under a power of attorney that cannot be checked and hurries the deposit. Each sign alone is explainable, and together they are grounds to stop.
Ask to meet the owner in person and compare identity details with the register. Carry out the deal only with reliable professionals and under an official procedure that does not allow money to be handed to unknown people.
The order of checks before the first payment
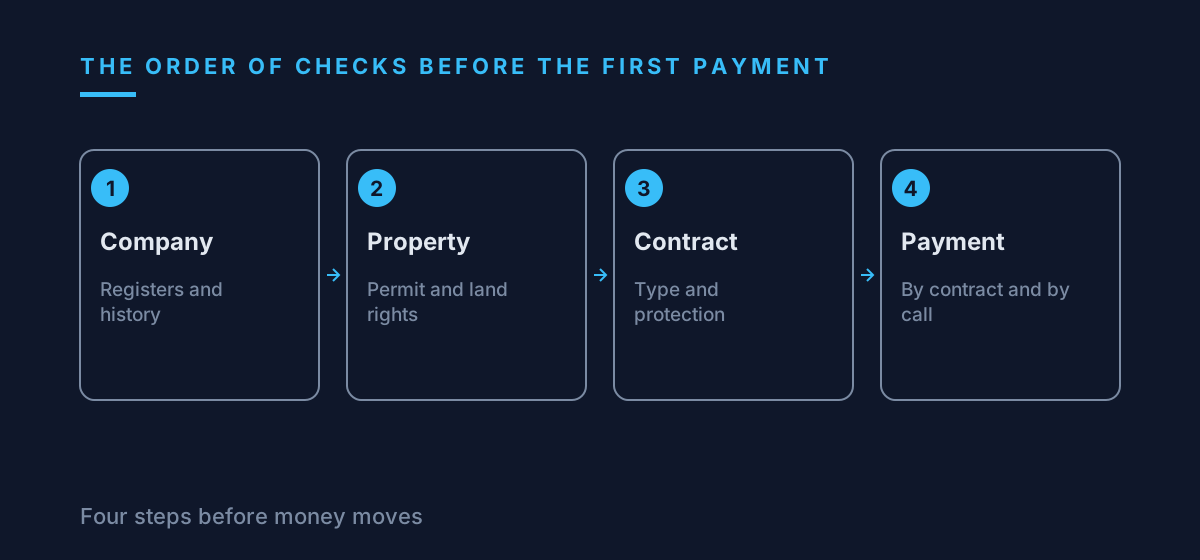
First check the legal entity and its history: how long it has existed, how many buildings it has delivered and whether it has disputes with buyers. Then check the property: the permit, the rights to the land, the type of contract and the mechanism protecting the money. After that read the contract to the last page.
Only then move on to money. Pay under the contract, to the account named in the contract, and confirm the details by phone. Keep all correspondence and payment documents so that a dispute can be reconstructed event by event.
If at any step something does not add up, stop. A good deal withstands a pause and extra questions. A deal that absolutely must happen today most often fails the check.
Where to report in the US
File a complaint at ic3.gov whatever the amount and report the scam to the FTC at ReportFraud.ftc.gov. Call the bank that sent the wire and ask for a recall at once, and tell the title company and the lawyer so that the other side of the deal is protected. Keep the email with the changed instructions, the wire confirmation, the call times and the names of everyone you spoke to.
A buyer who has not yet paid can take the check one step further by confirming the instructions in person or by a number agreed in advance, and by asking the bank whether the account name matches the company that is supposed to receive the money.
Write the verification down in the deal file: who you called, on which number, at what time and what they confirmed. If something goes wrong later, a clear record shortens the conversation with the bank, the title company and the investigators, and it shows that the instructions were checked before the money moved.
Checking a developer and a deal in the US: what to check, where and which sign should worry you
| What to check | Where | Warning sign |
|---|---|---|
| Payment instructions | A call to a number agreed in advance | New wiring details in an email |
| The people on the deal | Two trusted contacts named in advance | A last minute change of contact |
| The seller or builder | Public records and licenses | Pressure to pay before checks |
| Reviews | Independent sources | Identical praise in one month |
| The wire | Your bank, at once | Delay after the first suspicion |
| The complaint | ic3.gov and the FTC | Waiting for the other side to act |
Questions and answers
- Can I trust reviews of a developer?
- As a supplement. They show the impressions of residents, while the developer's status, permits and contract type are checked in official registers and documents.
- What should I do if an email arrives with new payment details?
- Call a number that was known before the email and confirm the details. Do not pay to details from an email without a call.
- What should I do if I sent a wire to a fraudster at closing?
- Contact your bank immediately and ask for a recall, then file a complaint at ic3.gov. The FBI froze 679,013,183 dollars in 2025 in cases reported quickly.
- What does the CFPB advise for a mortgage closing?
- Name two trusted people, distrust last minute changes, do not use phone numbers or links from an email and do not email financial information.
- Where do I report real estate fraud in the US?
- File at ic3.gov and report to the FTC at ReportFraud.ftc.gov, and call your bank at once.